2026-10-13
Europe’s SAF market ‘risks creating new dependence on China’
Europe risks creating a new strategic dependence on China and other overseas feedstock suppliers as it scales up sustainable aviation fuel (SAF), Nova Pangaea’s Latvian partner NorSAF has warned.
The company, which is building the Baltics’ largest SAF project, is urging Europe to make domestic production and locally sourced feedstocks more investable.
The warning comes as the European Union accelerates its SAF mandate while more than 50 advanced SAF projects across Europe remain unable to reach Final Investment Decision (FID), the point at which investors commit the capital needed to build them.
Under EU rules, the share of SAF supplied at EU airports must rise from 2% in 2025 to 6% in 2030 and 20% by 2035. But meeting those targets will require more than increasing consumption. Europe must also build the production capacity and feedstock supply chains needed to reduce reliance on imports, strengthen domestic industry and help bring down the long-term cost of decarbonising aviation.
Much of today’s European-produced SAF is made using HEFA (Hydroprocessed Esters and Fatty Acids), which relies heavily on feedstocks such as used cooking oil. EASA data shows that around 85% of the feedstocks used for SAF supplied at EU airports in 2025 came from outside the EU, with China accounting for 61% of imported feedstocks.
As demand for used cooking oil and other HEFA feedstocks increases globally, Europe risks competing with other emerging SAF markets for a finite supply. Advanced SAF pathways – such as Nova Pangaea’s technology – offer a way to diversify production by using agricultural and forestry residues and other non-food feedstocks that can be sourced closer to production plants.
NorSAF believes Europe should not only increase SAF consumption, but also build more of the feedstock, production capacity and economic value within the region. SAF production must also avoid competing with food and feed production. Food and feed crop-based feedstocks are not eligible under ReFuelEU Aviation, which further highlights the need to diversify production pathways.
The gap between mandated demand and investment is becoming increasingly important as the EU prepares to review its SAF framework. Without greater certainty around future demand, pricing and the duration of support, projects capable of diversifying Europe’s feedstock base risk remaining on the drawing board.
Janis Kielis, founder and board member of NorSAF, said:
“China is already building out its domestic SAF industry, with 10 SAF plants operational, and is increasingly looking to use its own feedstocks to produce SAF at home. The day may come when China no longer exports the used cooking oil Europe relies on but instead sells us the finished SAF. We cannot simply replace one dependency with another. Europe needs to at least triple its domestic SAF and eSAF production in the coming years, using feedstocks and energy resources available within Europe. But that will only happen if projects can attract investment.
“More than 50 SAF-related projects across the EU are awaiting final investment decision (FID). The ReFuelEU Aviation review must give financial partners confidence about how much SAF Europe will need, the economics of that market and how long that demand will be supported. An example solution could be the introduction of a grant or similar financial support scheme specifically designed to help companies reach FID, getting through this development phase is often known as the ‘’valley of death’’ and the main reason many large-scale, complex and funding-intensive industrial projects fail to progress.”
The comments were made at an industry roundtable in Brussels which brought together SAF industry representatives including Nova Pangaea and NorSAF with European Commission officials and policymakers.
Jonathan Wood, CCO of Nova Pangaea, agrees that Europe needs to look beyond the most established SAF pathway.
“Not all SAF is created equal. HEFA is today the lowest cost and most established pathway because used cooking oil as a feedstock is relatively simple to convert into fuel; however, as capacity scales up so the availability of used vegetable oils will become more constrained. That’s why we need to develop and scale up production technologies to convert biomass wastes and residues into liquid fuels – these feedstocks are relatively lower cost and widely available – in contrast used cooking oil is predominantly sourced from Asia and has limited supply.
“Policymakers should set regulations based on the greenhouse gas emission reduction achieved versus fossil fuel, not just the amount of SAF supplied, because the level of emission reduction varies by feedstock and SAF production process used. Nova Pangaea’s REFNOVA technology produces a co-product biochar, which is a form of permanent carbon removal and makes the whole process carbon negative – the advanced SAF made from it delivers more than twice the emission reduction compared with other SAF production processes.”
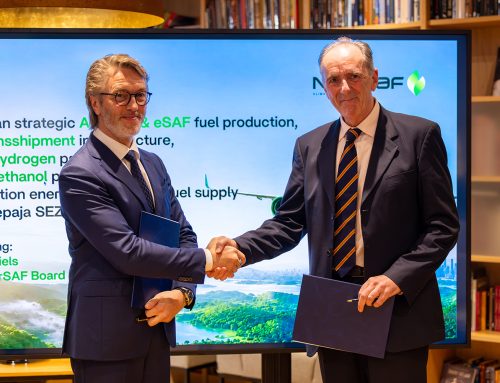
NorSAF and Nova Pangaea recently signed a memorandum of understanding (MoU) to develop an advanced bioethanol production plant in Latvia. The plant would use locally sourced forestry waste to create bioethanol to supply NorSAF’s planned SAF and eSAF facility. The partnership aims to unlock the potential of Europe’s waste biomass resources, strengthen EU-based feedstock supply chains and retain more economic value within Europe.
………………………………………………………………………………….
NorSAF’s proposed policy changes:
- Make domestic supply investable: Establish an Advanced SAF sub-mandate within ReFuelEU Aviation covering Annex IX Part A feedstocks, alongside the existing eSAF requirement, supported by stable eligibility rules and an EU framework for long-term offtake agreements and price-gap support.
- Align regulation with investment timelines: Link transitional eligibility for renewable hydrogen and synthetic fuels to FID rather than solely to commissioning, and extend SAF support under the EU Emissions Trading System beyond 2030 to support capacity coming online in the early 2030s.
- Build advanced European capacity: Support EU-origin feedstocks and first-of-a-kind projects through investment support and public risk-sharing guarantees, while encouraging a broader mix of technologies and production regions.